Is Xero Payroll Right for My Small Business?
As your business grows and you begin to employ staff, payroll quickly becomes one of the most important financial tasks to manage correctly. Paying employees accurately and on time, calculating income tax and National Insurance, and meeting HMRC compliance requirements can become increasingly time-consuming without the right systems in place.
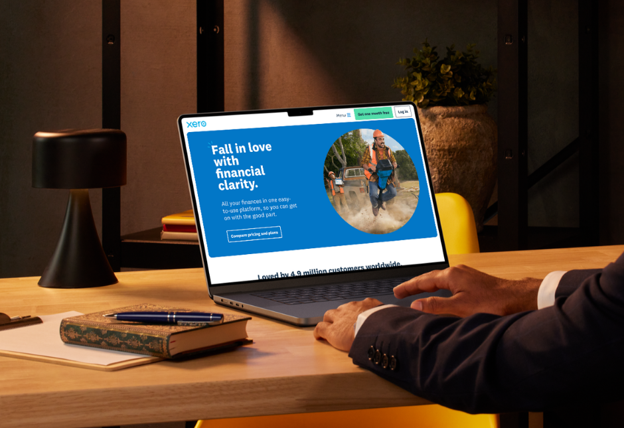
For many UK businesses, Xero Payroll offers a cloud-based payroll solution that integrates directly with Xero Accounting. But is Xero Payroll right for your small business? This guide explores its features, pricing, benefits, limitations and when it makes sense to choose Xero Payroll over other payroll providers.
What is Xero Payroll?
Xero Payroll is a cloud-based payroll software solution designed primarily for small businesses. It integrates seamlessly with Xero Accounting, allowing payroll data to flow directly into your accounting software without manual data entry.
Instead of managing payroll separately from your bookkeeping, Xero Payroll combines payroll processing, bank reconciliation and financial reporting within one platform. Payroll journals can automatically sync with Xero Accounting, helping accountants and bookkeepers reduce administration and improve accuracy.
For businesses already using Xero Accounting, this all-in-one system creates a much smoother workflow.
What features does Xero Payroll includes?
Xero Payroll includes a wide range of payroll functionality designed to simplify payroll admin for UK businesses.
The software automates tax calculations, PAYE, National Insurance and workplace pension contributions. It also handles statutory sick pay, statutory maternity pay and pension auto enrolment, helping employers meet legal requirements without relying on manual calculations.
Each pay run automatically generates digital payslips for employees, while Real Time Information (RTI) submissions are sent directly to HMRC through online submissions.
Employees can also access Xero Me, allowing employee self-service through a mobile app where they can view payslips, update bank details, request leave and access employee information securely.
Payroll processing and HMRC compliance
One of the biggest advantages of Xero Payroll is its focus on HMRC compliance.
The software automatically calculates income tax using employee tax codes, calculates National Insurance contributions and submits Full Payment Submissions (FPS) through RTI submissions to HMRC.
Workplace pensions and auto-enrolment
Managing workplace pension obligations is another area where payroll software provides significant value.
Xero Payroll supports pension auto enrolment and automates workplace pension contributions for eligible employees. The software also produces compliance reporting for pension providers, helping businesses meet their legal obligations.
Guidance on pension auto-enrolment can be found through The Pensions Regulator.
For many small business owners, automating pension contributions removes one of the more complicated payroll tasks.
How much does Xero Payroll cost?
Xero offers tiered plans designed for different business sizes, with payroll functionality available as an add-on depending on the subscription tier.
At the time of writing, Xero Payroll pricing starts from £15 per month excluding VAT, with payroll features typically charged at £1.50 per employee. Businesses requiring additional accounting functionality may choose higher subscription tiers, with Xero's Premium plan estimated at around £55 per month, depending on the services selected.
Because pricing can change, businesses should always review the latest costs through the official Xero pricing pages before making a decision.
Benefits of Xero Payroll for small businesses
For many small businesses, the biggest advantage of Xero Payroll is automation.
Automated payroll solutions save time, reduce administration and minimise calculation mistakes. Xero Payroll automates wage calculations, bonus deductions, tax calculations and pension contributions while generating digital payslips automatically.
Payroll journals sync directly with Xero Accounting, eliminating duplicate data entry and reducing the risk of inconsistencies between payroll and financial records.
Businesses also benefit from automated bank feeds and integration with wider accounting processes, making cash flow management easier throughout the tax year.
According to Xero, many users report significantly faster payroll processing after switching to the platform, allowing business owners to focus on growth rather than administration.
Is Xero Payroll suitable for every business?
While Xero Payroll is an excellent choice for many small businesses, it is not necessarily the best payroll software for every organisation.
It is particularly well suited to straightforward payroll involving a relatively small number of employees. Sole traders who begin employing staff often find it a logical extension of their existing Xero accounting system.
However, businesses with complex payroll requirements, multiple pay rates, Construction Industry Scheme (CIS Scheme) deductions or extensive international transactions may require more specialist payroll providers.
Some users also report slower customer support response times during busy periods, and businesses with particularly complex payroll structures may benefit from dedicated payroll services.
Before choosing any payroll software, it is important to assess your payroll complexity, future growth plans and reporting requirements.
Comparing Xero Payroll with other payroll software
When comparing payroll software, businesses should look beyond monthly pricing alone.
Key considerations include ease of use, HMRC compliance, pension integration, employee self-service, reporting functionality, support for year-end reporting and integration with accounting software.
Solutions that automate tax calculations, automate payroll tasks and integrate directly with bookkeeping systems often provide better long-term value than standalone payroll software.
The best payroll software is not necessarily the cheapest, but the one that reduces administration while maintaining compliance and accuracy.
The importance of professional payroll support
Even with modern payroll software, employers remain legally responsible for payroll accuracy.
Employment law, tax codes, National Insurance, statutory payments and workplace pension regulations continue to evolve. Software helps automate calculations, but it cannot replace professional advice when unusual situations arise.
Working with experienced accountants and bookkeepers ensures payroll remains compliant, accurate and aligned with wider financial management.
At 10CA, we help UK businesses integrate Xero Payroll with their accounting processes while providing expert payroll services, tax advice and ongoing support. Whether you are running your first payroll or managing a growing workforce, our team can help you stay compliant while reducing payroll administration.
Conclusion
Xero Payroll is a powerful cloud-based payroll solution that integrates seamlessly with Xero Accounting, making it an excellent option for many UK small businesses. Its automation of PAYE, National Insurance, pension contributions, RTI submissions and payroll processing can save valuable time while improving accuracy.
However, businesses with more complex payroll requirements should carefully assess whether Xero Payroll provides all the functionality they need. Choosing the right payroll solution depends on your workforce, compliance obligations and future plans.
If you are considering Xero Payroll or want expert advice on payroll, accounting software and business finances, the team at 10CA can help you choose the right solution for your business.
Disclaimer
This article is for general information only and reflects UK payroll regulations and Xero product information available at the time of writing. Software features, pricing and legislation may change. Professional advice should always be sought before implementing payroll systems or making payroll-related decisions.